Categories
Buyer & Seller Tips, Mortgage & WealthPublished September 15, 2026
How Can Homeownership Build Equity and Long-Term Wealth?
How Can Homeownership Build Equity and Long-Term Wealth?
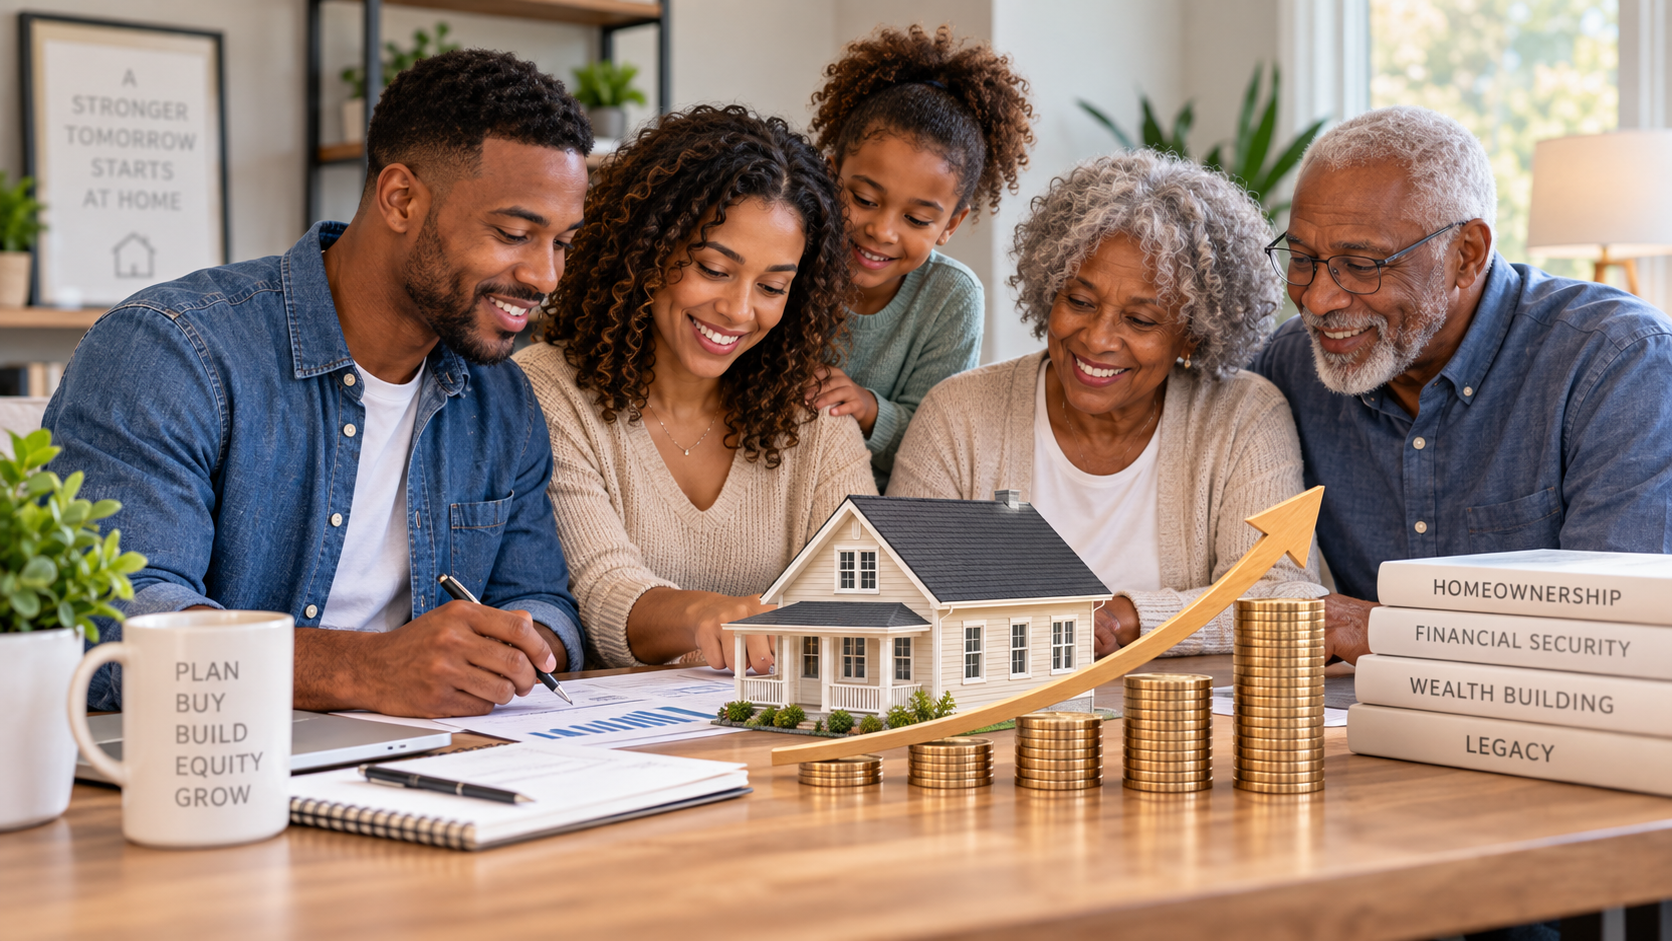
Homeownership may build wealth over time through two primary mechanisms: paying down mortgage principal and increases in property value.
It may also provide housing stability and a forced-savings effect for some households.
But homeownership does not guarantee investment returns. Property values can fall, homes require maintenance, and buying and selling involve real costs.
Mortgage Principal Reduction
With an amortizing mortgage, part of each principal-and-interest payment reduces the loan balance.
Early payments generally contain more interest than later payments, but principal reduction can gradually increase the homeowner's equity if the property's value remains stable.
Property taxes, homeowners insurance, association charges, and maintenance costs do not reduce the mortgage principal.
Property Appreciation
Appreciation means the property's market value increases over time.
Local supply, buyer demand, employment, interest rates, property condition, and neighborhood changes can all influence appreciation.
National or metropolitan trends do not guarantee a particular house's future performance. Treat appreciation as a possibility—not a promise.
What Household Wealth Data Shows
Federal Reserve Survey of Consumer Finances data shows a substantial difference between the median net worth of homeowners and renters or other non-homeowners.
That does not prove that purchasing a home by itself causes the entire difference. Homeowners and renters may also differ in age, income, savings, retirement assets, and other financial circumstances.
The useful takeaway is that home equity can become an important part of a household balance sheet over time.
Homeownership Has Costs Too
A realistic analysis should include mortgage interest, financing expenses, property taxes, insurance, maintenance, major system replacements, association dues when applicable, and the costs of eventually selling.
These expenses are one reason a short ownership period may produce a very different financial outcome than long-term ownership.
Buying Should Fit the Household
Homeownership may make sense when the household has sustainable income, manageable total debt, appropriate reserves, and a housing payment that leaves room for maintenance and other financial priorities.
Renting can also be the responsible choice when flexibility is important, reserves are limited, or ownership costs would stretch the household too far.
Start With the Right Numbers
Whether you already own a home or are considering your first purchase, the next decision should begin with accurate information—not a promise that buying automatically creates wealth.
Lisa Thames-Warfield, NMLS #252215.
Mutual of Omaha Mortgage, Inc., NMLS ID 1025894. Keller Home Loans is a division of Mutual of Omaha Mortgage, Inc., NMLS ID 1025894. 3131 Camino Del Rio North, Suite 1100, San Diego, CA 92108. KY Mortgage Company License MC707287. www.nmlsconsumeraccess.org.
Lisa Thames-Warfield
Realtor | Our Spaces Collaborative Group | Keller Williams Collective
or another way