Categories
Real Estate Resources, Community & Economic Development, Southern Indiana LivingPublished September 17, 2026
From Temporary Shelter to Your Own Front Door: Understanding VA Housing Grants, Rental Assistance, and the Path to Homeownership
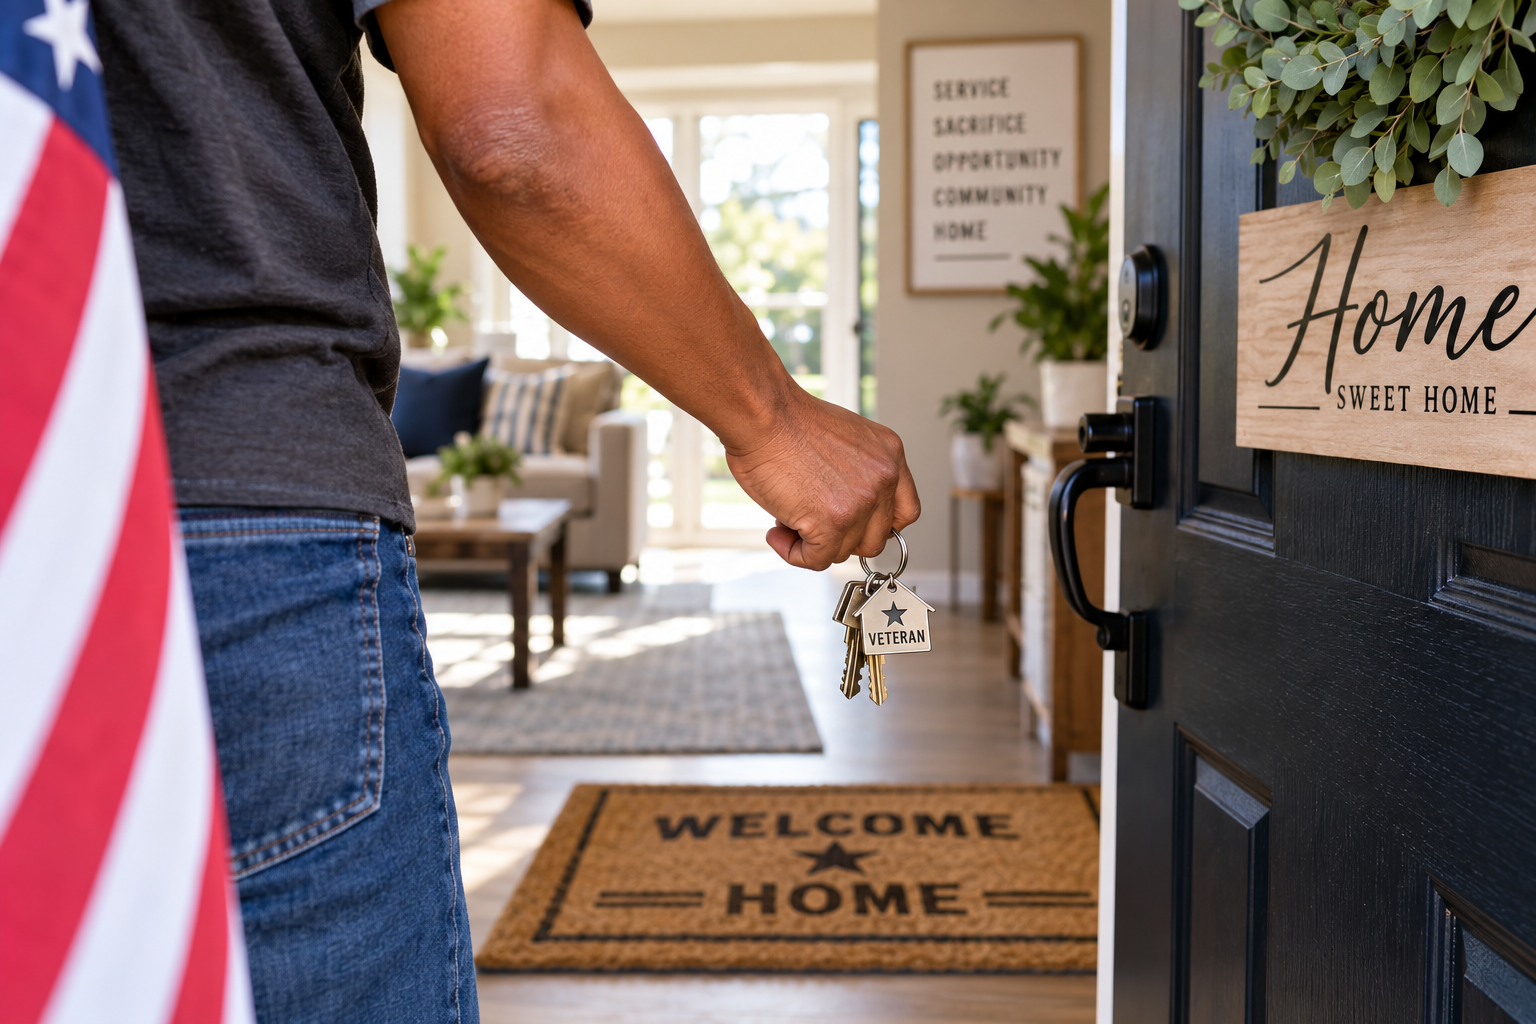
From Temporary Shelter to Your Own Front Door: Understanding VA Housing Grants, Rental Assistance, and the Path to Homeownership
When federal announcements release lists of Department of Veterans Affairs housing grants, the dollar amounts can look substantial.
But the terminology can also make it sound as though Veterans are receiving direct grants to purchase homes.
That is usually not what these programs do.
Many VA homelessness grants fund local nonprofit organizations and community providers that operate transitional housing, case management, rental assistance, and other services designed to help Veterans move toward permanent housing.
Understanding how these programs fit together can make the path from temporary shelter to long-term housing much easier to follow.
Phase 1: Immediate and Transitional Housing
The VA Grant and Per Diem Program, commonly called GPD, funds community organizations that provide transitional housing and supportive services for Veterans experiencing homelessness.
Rather than giving the grant money directly to an individual Veteran to purchase a home, VA funding helps approved organizations operate housing programs, provide case management, and connect Veterans with services.
Veterans may generally remain in GPD transitional housing for up to 24 months, although limited extensions may be available depending on individual circumstances and program rules.
What About Participant Fees?
A GPD supportive-housing provider may charge a participant fee, but federal rules limit that fee to no more than 30% of the Veteran's monthly income after certain allowable deductions.
Programs may also charge reasonable voluntary fees for certain extracurricular services that are not funded by the VA.
Because individual programs differ, Veterans should ask the provider directly about any participant costs before entering a program.
Phase 2: Moving Into Permanent Rental Housing
Transitional housing is intended to be temporary.
The next step for many Veterans is permanent rental housing, and two federal programs can play important roles in that transition.
Supportive Services for Veteran Families
The Supportive Services for Veteran Families program, or SSVF, helps eligible low-income Veteran households obtain or maintain permanent housing.
Depending on the household and program eligibility, assistance may include:
- Rental assistance
- Security deposits
- Utility assistance
- Moving expenses
- Housing case management
- Help locating permanent housing
Locally, Volunteers of America Mid-States operates SSVF programs serving both the Louisville area and Clark and Floyd Counties in Southern Indiana.
HUD-VASH
The HUD-Veterans Affairs Supportive Housing program, commonly called HUD-VASH, combines a HUD Housing Choice Voucher with VA case management and supportive services.
For eligible Veterans experiencing homelessness, the program can help make long-term rental housing more affordable while maintaining connections to VA services.
These programs are designed for housing stability—not home purchases.
But stability can create the foundation for a future homeownership conversation.
Phase 3: When Homeownership Becomes Part of the Plan
For some Veterans, homeownership may eventually become the next step.
VA homelessness programs themselves are not home-purchase grants.
However, eligible Veterans may be able to use the VA Home Loan Guaranty to purchase a primary residence.
A VA-backed purchase loan can often be made with no down payment when program, lender, appraisal, and eligibility requirements are met.
VA-backed loans also do not require monthly private mortgage insurance.
That can reduce one of the significant monthly costs associated with some other low-down-payment mortgage programs.
Veterans may also be able to explore state homebuyer-assistance programs.
In Kentucky, Kentucky Housing Corporation offers homebuyer programs that may assist with down payment and closing costs, subject to program eligibility and repayment requirements.
Indiana buyers can similarly review current programs offered through the Indiana Housing and Community Development Authority.
These programs change, and not every form of assistance is a grant. Buyers should verify current guidelines before making financial plans around a particular program.
When Is Someone Ready to Discuss Homeownership?
There is no single timeline.
The right time to explore homeownership depends on factors such as:
- Reliable qualifying income
- Credit history
- Existing debt obligations
- Housing goals
- Savings and reserves
- VA loan eligibility
- Applicable mortgage guidelines
A housing program, case manager, or supportive-service provider may help establish stability.
The mortgage conversation comes later, when the Veteran is ready to evaluate whether buying is financially appropriate.
Local Veteran Housing Resources
Veterans and service providers in Greater Louisville and Southern Indiana do not have to figure out the system alone.
Robley Rex VA Medical Center — Louisville
800 Zorn Avenue
Louisville, KY 40206
502-287-4000
The VA can connect Veterans with homelessness programs, housing coordinators, health services and other eligible benefits.
Volunteers of America Mid-States — SSVF, Louisville Metro
2820 W. Broadway, Suite 600
Louisville, KY 40211
502-384-0868
Volunteers of America Mid-States — Clark and Floyd Counties
2676 Charlestown Road, Suite 10
New Albany, IN 47150
502-384-0868, ext. 4
The SSVF program provides housing-focused case management and eligible temporary financial assistance to help Veterans obtain or maintain permanent housing.
National Call Center for Homeless Veterans
877-424-3838
The National Call Center provides free, confidential assistance 24 hours a day and can connect Veterans or people calling on their behalf with VA resources.
My Perspective
Housing recovery does not always move directly from homelessness to homeownership.
There may be several steps in between.
Temporary housing can provide safety.
Rental assistance can provide stability.
Case management can help someone rebuild income, credit, and financial capacity.
And for Veterans who eventually reach the point where buying a home makes sense, the VA home loan benefit can become another tool in that longer housing journey.
Understanding which program solves which problem is important.
A shelter grant is not a mortgage program.
A rental voucher is not a down payment program.
And a VA-backed mortgage is not a substitute for the supportive services someone may need earlier in the process.
But together, these resources can form parts of a much larger path toward stable housing.
Looking Ahead to Homeownership?
If you are a Veteran, case manager, or service provider trying to understand how VA-backed financing may fit into a longer-term housing plan in Greater Louisville or Southern Indiana, schedule a real estate and home-financing strategy conversation with Lisa Thames-Warfield and Our Spaces Collaborative Group.
Mortgage information is provided for educational purposes only and is not a commitment to lend. Eligibility, loan amount, interest rate, costs and program availability depend on borrower qualifications and applicable program guidelines.
Lisa Thames-Warfield, NMLS #252215. Mutual of Omaha Mortgage, Inc., NMLS ID 1025894. Keller Home Loans is a division of Mutual of Omaha Mortgage, Inc., NMLS ID 1025894. 3131 Camino Del Rio North, Suite 1100, San Diego, CA 92108. KY Mortgage Company License MC707287. www.nmlsconsumeraccess.org.
Lisa Thames-Warfield
Realtor | Our Spaces Collaborative Group | Keller Williams Collective
or another way